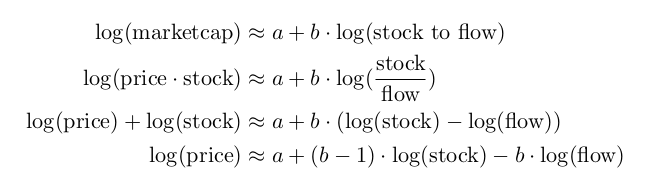
Showing posts with label WHAT’S. Show all posts

Thursday, November 3, 2022

DeFi vs. CeFi: What's the Difference Between Decentralized and Centralized Finance?

The crypto environment is made up of both central and decentralized financing, 2 sectors that provide different monetary product or services. This guide will compare CeFi vs. DeFi and highlights their particular chances and downsides.

What is Centralized Finance (CeFi)?

On the surface area, centralized financing (CeFi) resembles conventional financing (TradFi) considering that a user handles relied on intermediaries. The 2 aren't the very same.

TradFi includes tradition organizations that have actually existed for centuries and will venture into the digital possession area, while CeFi describes digital property business that use crypto-related services and products

Among CeFi platforms, there are central crypto exchanges (CEXs), crypto loaning business, and digital currency payment suppliers. They supply custodial hot wallets to their users. That indicates the platforms really hold the personal secrets of their users' wallets and are, for that reason, in control of their crypto properties. That leaves users at the grace of these platforms ought to the latter choose to suspend their customers' accounts and obstruct their withdrawals.

Users are likewise based on the guidelines that CeFi business make. These guidelines are generally made behind closed doors, simply as holds true in the conventional world of financing with personal business. They choose what guidelines their consumers need to follow and which coins will be noted.

Additionally, CEXs usually need users to finish the Know Your Customer (KYC) procedure prior to they can begin trading.

CeFi is a simple point of entry for crypto newbies since of its resemblances to TradFi. Prior to DeFi emerged, centralized financing platforms were the traditional locations users would opt for trading cryptocurrency

What is Decentralized Finance (DeFi)?

In CeFi, clients put their rely on intermediaries, while DeFi eliminates these intermediaries and changes them with clever agreement procedures.

DeFi, which is brief for decentralized financing, brings more decentralization to the world of financing by making sure that digital properties can be traded on decentralized platforms.

DeFi makes it possible for the trading of peer-to-peer monetary items through decentralized applications (DApps) using services on the blockchain. These product or services are supplied by applications developed on existing blockchains such as Ethereum, BNB Chain, Tron, Avalanche, and Solana. The applications are developed utilizing wise agreements, which figure out the guidelines the DeFi procedure is operating by.

Just like CeFi and TradFi, DeFi provides trading, loaning, and loaning services. There are a number of distinctions.

Firstly, operations on DeFi procedures operate on code. Users can engage with DeFi procedures through non-custodial wallets. That method, they stay completely control of their crypto possessions. There's no requirement to sign up an account and total KYC to utilize DeFi services. Users just require to link a wallet to begin utilizing DeFi procedures.

CeFi vs. DeFi: A Comparison

The table listed below programs a side-by-side DeFi vs. CeFi contrast.

Criteria CeFi DeFi
Regulatory Compliance Abides by guidelines in the nation where it runs, following KYC, anti-money laundering, and combating the funding of terrorism requirements. Remains mainly uncontrolled.
KYC Users should reveal their individual info through a KYC procedure to utilize CeFi platforms. KYC isn't needed.
Third-party Reliance Users depend upon relied on 3rd parties to gain access to monetary product or services. DeFi users do not count on 3rd parties to gain access to monetary product or services.
On-ramps The offered on-ramps are fiat-to-crypto and crypto-to-crypto. DeFi just permits crypto-to-crypto on-ramps.
Custody Users are not in control of their crypto properties. Users are in control of their crypto possessions which requires a greater level of obligation and care to keep them safe.
Platform Development The business behind CeFi platforms are typically signed up in the jurisdictions they run. The designers behind some DeFi procedures are confidential or pseudonymous, and there is yet a regulative dispute about whether they need to be made responsible in a manner.
Transparency Decisions are made behind closed doors. CeFi platforms might not expose their trading procedures and rate development practices. They keep their systems off-chain. Deals within the exchange aren't taped on the blockchain All deals are taped on the blockchain and show up to everybody as far as public blockchains are worried.
Security CeFi platforms are susceptible to security breaches. Bugs in clever agreements might be made use of to take user funds.

CeFi Examples

CeFi platforms provide a large range of crypto financial investment services. Here are a few of the leading services offered and the platforms that use them.

Spot Trading

CEXs that provide area trading services enable users to purchase and offer crypto possessions for instant shipment. Area trading is available on many CEXs like Coinbase, Kraken, Binance, KuCoin, Huobi Global, and FTX.

Derivatives Trading

Crypto derivatives like futures, continuous agreements, and alternatives are supplied by numerous CEXs. Binance, Deribit, Bybit, and BitMEX make it possible for users to trade continuous and futures agreements. Derivatives enable traders to hypothesize on the rate of the underlying crypto possession.

Asset Management

Asset management provider such as Grayscale Investments, Galaxy Digital, BlockFi, and Bitwise handle crypto properties on behalf of their customers.

Staking

Crypto users can stake their coins-- lock them for a specific period-- on CEXs like Gemini, Binance, Coinbase, KuCoin, and Kraken to make staking benefits.

Borrowing

Borrowing digital properties is possible on platforms that mainly concentrate on crypto loans, like CoinRabbit, Nexo, and Nebeus. They allow users to obtain cash (fiat or crypto) versus their crypto properties, which are utilized as security in the loan.

DeFi Examples

DeFi procedures concentrate on a varied variety of services, consisting of those noted below.

Token Swapping

Token switching or trading occurs on decentralized exchanges (DEXs) like Curve, Uniswap, PancakeSwap, SushiSwap, and Balancer. These procedures are developed on several blockchains. Curve is readily available on about 11 chains, while Uniswap is on 5.

Lending and Borrowing

Lending and loaning procedures assist crypto users provide their idle crypto possessions and make interest in return. Users can likewise obtain digital possessions versus their crypto holdings and pay interest to lending institutions. Aave, Compound, JustLend, Venus, Solend, and Tectonic are examples of financing and loaning platforms from within the DeFi sector. They might be developed on several blockchains.

Liquid Staking

Lido, Rocket Pool, Marinade Finance, Ankr, and Staker are procedures where crypto users stake their properties and make benefits. Users' stakes are tokenized, allowing them to switch the tokenized stake back to the initial token whenever they desire out (this is not yet the case for ETH). Liquid staking procedures might exist on several chains.

Collateralized Debt Position

Collateralized financial obligation position(CDP) procedures allow users to mint stablecoins by locking security in a wise agreement. CDP procedures consist of MakerDAO, JustStables, Kava Mint, Abracadabra, and QiDAO. These DeFi procedures might be developed on several blockchains.

Bridging

Bridging procedures link blockchains, enabling the motion of crypto possessions in between them. WBTC, Multichain, JustCryptos, Poly Network, and Portal are examples of bridging procedures. DeFi procedures might be readily available on several chains. Keep in mind that such bridging procedures are still extremely centralized. That method, they differ more decentralized DeFi procedures like Uniswap or Aave.

CeFi vs. DeFi: Pros & & Cons
CeFi

Pros

Familiar: CeFi platforms run like conventional monetary providers. This indicates many people will discover them familiar and fairly simple to utilize.

Fiat-to-crypto assistance: You can quickly purchase crypto on a central crypto exchange with your regional currency. CEXs support numerous fiat currencies based upon where they run.

Cons

Custodial: CEXs are in control of the digital possessions in their users' wallets/accounts considering that they hold their personal secrets. Without these personal secrets, users can be rejected access to their properties if the platform suspends withdrawals and deposits.

Personal details is needed: Users need to be all set to share their individual info, such as names, domestic addresses, nationwide ID information, and selfie photos, to utilize CEXs.

Lack of openness: CeFi business make their choices behind closed doors. Hence, users might not understand what trading practices they utilize. Their systems are off-chain, which indicates deals within the exchange are not taped on the blockchain.

Restrictive: CEXs are not available to everybody due to the fact that they might have area constraints. Particular exchanges might not enable individuals from particular (black-listed) nations to trade on their platform. A few of these limitations might be executed due to regulative requirements.

DeFi

Pros

Self-custody: Crypto users are in control of their properties due to the fact that they hold the personal secrets. That suggests nobody can obstruct access to their funds.

Privacy: DeFi users take pleasure in personal privacy due to the fact that their individual details isn't needed, and the wallet they utilize is not linked to their genuine identity.

Permissionless: Anyone can utilize DeFi items as long as they have a wallet and a web connection. There are no constraints.

Transparent: DeFi deals show up on the blockchain for public watching. This produces openness for users.

Cons

Smart agreement danger: Attackers might make use of vulnerabilities in the clever agreement to take crypto possessions locked within a DeFi procedure.

Steep discovering curve: DeFi procedures are brand-new and non-traditional. Novices might discover them hard to utilize or comprehend. That implies individuals need to take their time to comprehend DeFi and the items provided prior to they can begin communicating with them.

Scalability: DeFi procedures count on the blockchains on which they are developed on. They acquire the scalability problems of such blockchain networks. Scalability problems consist of low deal throughputs, which causes high deal charges when the network is crowded.

What's Better?

It's challenging to state which of the 2 choices to do financing is much better due to the fact that they both have their benefits and drawbacks. After all, it depends upon the requirements of various users.

To show, those who value monetary sovereignty and personal privacy might select DeFi procedures, while institutional financiers normally choose controlled CeFi platforms. This might discuss why CeFi and DeFi have actually been co-existing together for several years.

In theory, decentralized financing is most likely the much better of the 2 for crypto financiers. The DeFi market is yet to reach the level of maturity where it is truly safe to utilize for financiers.


Read More https://bitcofun.com/defi-vs-cefi-whats-the-difference-between-decentralized-and-centralized-finance/?feed_id=48259&_unique_id=63648f453103b

Wednesday, September 28, 2022

What's Going On With y00ts?

The y00 ts NFT mint has actually suffered problems, however interest for the collection isn't subsiding.

Key Takeaways

  • The main Twitter for the y00 ts NFT collection mentioned today that waitlisted individuals would not have the ability to mint their NFTs today as initially prepared.
  • Whitelisted candidates had actually likewise suffered a hold-up for their own mint.
  • t00 bs NFTs, which will quickly be exchangeable for y00 ts, are presently the leading traded collection on OpenSea.

Waitlisted candidates for the y00 ts mint will not have the ability to get their NFTs today, the main y00 ts Twitter account specified. A 24- hour notification will be offered prior to the mint goes live.

y00 ts, t00 bs, and DeGods

NFT minting procedures are complicated as ever, and one hotly-anticipated task has actually struck a couple of snags.

The main Twitter account of the y00 ts NFT collection published an upgrade today showing that waitlisted y00 ts fans would not have the ability to mint their NFTs today as formerly revealed. The account did not state when the mint will happen, however assured that a 24- hour notification would be provided.

Whitelisted candidates (not to be puzzled with the waitlisted ones) were currently able to mint their NFTs the other day; their mint, at first prepared for September 4, had actually likewise been postponed after the group experienced a "blocker bug" in the software application. Numerous neighborhood members talked about the quality of the minting experience, with some calling it smooth and others grumbling of prolonged problems. "Admittedly, minting has actually never ever been our strong point," acknowledged the collection creator, who passes Frank on Twitter.

The y00 ts launch has actually been commonly prepared for in the NFT area. DeGods, an associated NFT collection likewise developed by Frank, reached record rates on September 1 in spite of the ruthless bearish market dragging most NFT collections down. Initially minted on October 8, 2021 at a cost of 3 SOL, the most affordable DeGods are presently trading for 479 SOL (worth about $14,849) on OpenSea and 450 SOL ($13,950) on Magic Eden Day-to-day trading volume is presently at 13,511 SOL.

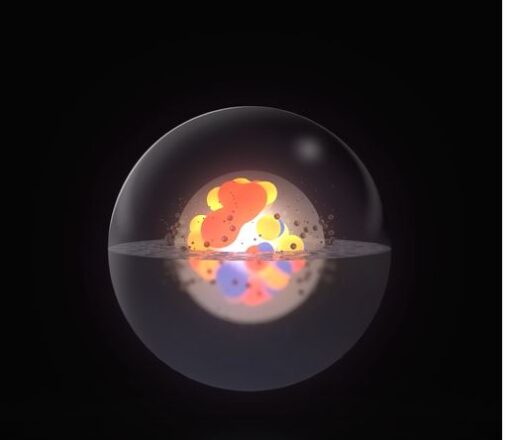
Early y00 ts minters were granted mystical "t00 b" NFTs; the art work presently looks like an orb with a multi-colored, ringed planet-like item spinning in it. The previous launch plan suggested that the t00 b expose (in which t00 b NFTs will be burned in exchange for appropriate, special y00 ts NFTs) would take place on September 9, though it's possible it will now be delayed as an effect of the task's previous hold-ups.

A t00 b (#8524). Source: OpenSea

The least pricey t00 bs are currently trading for 160 SOL (about $4,960) on OpenSea and 138 SOL ($ 4,278) on Magic Eden Its trading volume of 189,900 SOL made t00 bs the leading traded collection on OpenSea in the last 24 hours.

Disclaimer: At the time of composing, the author of this piece owned ETH and a number of other cryptocurrencies.

The details on or accessed through this site is gotten from independent sources our company believe to be precise and dependable, however Decentral Media, Inc. makes no representation or guarantee regarding the timeliness, efficiency, or precision of any details on or accessed through this site. Decentral Media, Inc. is not a financial investment consultant. We do not provide customized financial investment guidance or other monetary recommendations. The info on this site undergoes alter without notification. Some or all of the details on this site might end up being out-of-date, or it might be or end up being insufficient or unreliable. We may, however are not bound to, upgrade any out-of-date, insufficient, or incorrect details.

You need to never ever make a financial investment choice on an ICO, IEO, or other financial investment based upon the info on this site, and you ought to never ever translate or otherwise depend on any of the info on this site as financial investment recommendations. We highly suggest that you seek advice from a certified financial investment consultant or other certified monetary expert if you are looking for financial investment suggestions on an ICO, IEO, or other financial investment. We do decline payment in any type for examining or reporting on any ICO, IEO, cryptocurrency, currency, tokenized sales, securities, or products.

See complete conditions

Invisible Friends NFTs Soar 5,00 0% as Mint Goes Live

News

The extremely expected Invisible Friends NFT collection released last night. The art work is yet to be exposed, NFTs were quickly trading at a 5,00 0% mark-up on the secondary market ...

Invisible Friends NFTs Soar 5,000% as Mint Goes Live

Moonbirds Set to Bring in $66 M as NFT Drop Mints Out

News

The Moonbirds group has actually guaranteed the NFTs will use energy within the PROOF community. Moonbirds Set to Mint Out The NFT area remains in a craze over this weekend's huge ...

Moonbirds Set to Bring in $66M as NFT Drop Mints Out

NFT Opportunists Are Making a Mint Through an OpenSea Bug

Collectors of high-value NFT collections are accidentally offering their possessions at big discount rates due to an OpenSea listing bug. Blue Chip NFTs Lost Due to OpenSea Bug A bug on ...

NFT Opportunists Are Making a Mint Through an OpenSea Bug


Read More https://bitcofun.com/whats-going-on-with-y00ts/?feed_id=40251&_unique_id=63346b2e47ecf

Saturday, July 23, 2022

What's Next For Bold Bitcoin-Buyer MicroStrategy?

MicroStrategy (MSTR) presently rests on a big loss on their bitcoin purchases. Based upon a present bitcoin rate of $20,300, their 129,699 aggregate bitcoin holdings deserve $2.6 billion, below an overall purchase expense of approximately $4 billion (typical expense $30,700). They are sitting on latent losses of ~$ 1.4 billion on their purchases.

The last number of years have actually been a wild trip for MSTR investors, and paradoxically, the share rate ($186) does not sit that far above the share rate in the summertime of 2020 when they revealed their very first bitcoin purchase (around $140).

Michael Saylor has actually appeared bemused by the constant speculation online at MSTR having their bitcoin holdings liquidated at around $21,000 due to the current $200 million loan with Silvergate. Even looking for Michael Saylor's name on Twitter raised the auto-complete expression "Michael Saylor liquidated."

This speculation is quite deceptive, however even still, where does the current market chaos in Bitcoin leave them? To consider this, let's merely detail the regards to the different financial obligations they have actually handled in the last number of years, consisting of that Silvergate loan.

First Convertible Note Offering-- December 2020

MicroStrategy Completes $650 Million Offering of 0.750% Convertible Senior Notes Due 2025

The very first convertible note offering was for $650 million, due in December2025 The rates of interest payable for these by MSTR was simply 0.75%, making the maintenance of this financial obligation quite easy-- simply under $5 million interest expense annually.

Hence, these convertible bond holders are not getting much interest, however they do have the alternative to transform their financial investment to MSTR shares at $398 per share. Therefore this represents a kind of call alternative on the future cost of MSTR shares, albeit one which is now worth less at present market value.

To highlight the convertible part, let's state MSTR stock is priced at $500 per share at the redemption date in Dec 2025-- if you had $1 countless convertible notes they would then deserve $1.25 million, considering that you might purchase the shares for $398 and instantly offer them for $500 This, and other upside situations, describe the low rate of interest payable.

Second Convertible Note Offering-- February 2021

MicroStrategy Completes $1.05 Billion Offering of Convertible Senior Notes Due 2027 at 0% Coupon and 50% Conversion Premium

This offering (which raised $1.05 bn) is much along the exact same structure as the very first, albeit at even much better terms from an MSTR perspective, and even worse terms for the convertible bond holders. This time, the rates of interest is 0%, so there is no interest expense and the redemption date remains in February 2027.

The convertibility for these notes just consists of worth if the share rate of MSTR is above $1,432 per share-- thus much less most likely to be transformed than the previous offering. It appeared relatively most likely at the time, offered the stock cost closed at $955 on February 16,2021

Skeptics will question the virtue of raising this much financial obligation to purchase bitcoin, however one component appears clear in hindsight-- MSTR and Michael Saylor got a respectable handle loaning on these terms at the time.

Senior Secured Notes-- June 2021

MicroStrategy Completes $500 Million Offering of 6.125% Senior Secured Notes Due 2028 With Bitcoin Use Of Proceeds

This represented a more traditional bond offering. MSTR obtained $500 million up until 2028, at a yearly rates of interest of 6.125%. This makes the yearly interest expense of these bonds around $306 million, significantly more than the previous convertible notes interest expense integrated.

This statement likewise accompanied the facility of a subsidiary-- "MacroStrategy"-- which would hold the existing 92,079 bitcoin that they owned. While the brand-new financial obligation was senior protected notes-- having a high concern of being paid versus other lenders in case of future insolvency-- most importantly they are not protected versus the 92,079 bitcoin. This ends up being appropriate when we think about the later Silvergate bitcoin-backed loan.

Silvergate Bank Loan-- March 2022

This loan was somewhat various-- obtaining $205 million for 3 years which is backed by the MacroStrategy-held bitcoin. As connected to in slides 11 and 12 in this discussion, this was at first backed by 19,466 bitcoin, however more can be particularly promised as security needs to the cost of bitcoin fall.

First Quarter 2022 Financial Results Presentation

The "leading up" loan-to-collateral-value ratio is 50%. It is this reality that has actually most likely led numerous to mention the MSTR liquidation cost on the loan as the rate of bitcoin falling listed below $21,000-- at this moment the 19,466 bitcoins would deserve listed below $410 million (2 x 205), and they would require to promise more collateral under the regards to the loan. As Michael Saylor pointed out and the slides above program, there are a more 95,643 bitcoins which have actually not yet been vowed, and might be.

Linked MicroStrategy Investor Relations Tweet.

The mathematics works as follows concerning the $3,562 referenced in the tweet. At that cost point the overall 115,109 bitcoin offered to back the loan would be just worth $410 m, so MicroStrategy would need to promise some other security to keep the 50% loan-to-value ratio going.

How about the interest expense on this loan? It's based upon the 30- day typical SOFR (Secured Overnight Funding Rate) plus 3.7%. At the time of composing (end of June, 2022) SOFR has to do with 1%, so this makes 4.7% overall. Based upon 4.7% interest, it would cost them about $9.6 million each year to service the interest presently. The 1% SOFR rate is anticipated to go higher. More SOFR increases would not show too material however-- at 4%, for instance, (and thus 7.7% overall) the interest expense would be $158 million.

Conclusions

So what can we conclude from all this?

1. The interest expenses in overall from all the financial obligation raised to purchase bitcoin appearance workable, amounting to around $45 million ($ 5m + $0 + $306 m + $9.6 m) each year at present. This looks budget friendly to service-- the current quarterly outcomes reveal gross revenue for the current quarter at $94 million.

MicroStrategy Announces First Quarter 2022 Financial Results

2. Even offered substantial current decreases in the rate of bitcoin, MSTR's holdings need to not be affected by the rate in the short-term, unless it falls enormously, to $3,500 k. This is because of the large quantity of bitcoin they have offered to back the Silvergate loan, to keep the support at a 50% loan-to-value ratio.

3. What is obviously striking is the existing substantial on-paper loss that MSTR is resting on in regards to its bitcoin purchases, considered that their typical expense basis is $30,700 per bitcoin. It would no question show an issue for them if the bitcoin rate stays listed below this in the longer term and a few of the financial obligation begins to near redemption. The very first loan due is the Silvergate loan in March2025 Offered this is with bitcoin backed as security, it might really be possible to roll this over in a comparable style.

The next due is the very first convertible note offering in December2025 If MSTR is still resting on substantial bitcoin losses at this moment, they might discover it difficult to roll over that $650 million financial obligation in the market. It would cause a challenging choice as they would most likely wish to prevent offering any bitcoin at a loss in order to repay the financial obligation.

One element is quite on their side, though: In the world of Bitcoin, or certainly even the larger macroeconomic environment, December 2025 seems like a long time away.

4. It appears not likely that MSTR would look for (or certainly be able) to raise far more financial obligation in present market conditions-- as Michael Saylor mentions in the interview clip listed below, they obtained formerly on quite useful terms. It likewise appears not likely today that they would offer extra equity into the marketplace to purchase more bitcoin, which they have actually likewise done formerly, as the share cost is presently so low.

5. They might continue purchasing more bitcoin with earnings and undoubtedly, while composing this, MSTR did reveal an additional little bitcoin purchase of $10 million.

6. What promises along with this is deciding to keep some future revenues in dollars for optionality over the next number of years instead of purchase more bitcoin with it, regardless of bitcoin's lower cost. The Q1 2022 results connected above (see point 1) would recommend that they are presently constructing some money reserves, holding $93 million in money versus $63 million 3 months previously.

7. One last alternative would be to redeem a few of their own show make money from business, considered that their share rate has actually decreased by a greater percentage over the last 6-12 months than the bitcoin rate. This basically would send out a signal that the marketplace underestimates MSTR relative to even the bitcoin cost, and would make up a bold, albeit dangerous, program of faith in their technique.

Finally, it deserves seeing this video link from CNBC for some current ideas from Michael Saylor, that includes the following quotes:

Interviewer: "Would you think about purchasing more?"

Michael Saylor: "Yeah. If your time horizon is one month, then Bitcoin appears like an unstable danger property. If your time horizon is 10 years, it looks like a threat off shop of worth possession ..."

" ... we obtained 2.2 billion dollars at a mixed interest rate of 1.8% prior to interest rates doubled. It looked like a sensible thing to do. $1.7 billion is unsecured, the rest is a 7 year term after we obtained the cash. The margin loan is well handled ..."

" ... Bitcoin is the very first and just genuine deficiency in deep space."

None of the material in this post must be interpreted as monetary suggestions or taken as a recommendation to purchase or offer shares in MSTR. The author owns shares in MSTR.

Thanks to Will Schoellkopf for examining this post.

This is a visitor post by BitcoinActuary. Viewpoints revealed are totally their own and do not always show those of BTC Inc. or Bitcoin Magazine


Read More https://bitcofun.com/whats-next-for-bold-bitcoin-buyer-microstrategy/?feed_id=29687&_unique_id=62dcacfc9669b

Wednesday, July 13, 2022

3AC Is Broke. What's Next for Its Multi-Million Dollar NFT Collection?

Key Takeaways

  • The contagion from Three Arrows Capital's continuous liquidation might infect its associated NFT fund, Starry Night Capital.
  • Starry Night Capital was established in August 2021 and looked for $100 million to purchase high-end NFTs.
  • Whether Starry Night will be required to offer its collection is not yet clear, however a liquidation would likely lead to a substantial understood loss for the fund.

Crypto Briefing checks out whether Starry Night Capital will be required to liquidate its prominent NFT collection and the effect that such an occasion might have on the NFT area.

3AC Faces Liquidation

Three Arrows Capital is dealing with personal bankruptcy, however it's presently keeping a multi-million dollar collection of popular NFTs.

The distressed crypto hedge fund widely referred to as 3AC initially awakened issue in the crypto neighborhood in early June as reports flowed online that it had actually stopped working to satisfy margin contact numerous of its loans. On Jun. 17, Kyle Davies, who co-founded the company with his high school schoolmate Su Zhu in 2012 informed The Wall Street Journal that the fund was thinking about property sales and a prospective bailout in order to settle its financial obligations. He likewise exposed that it had actually lost over $200 million in Terra's collapse and the subsequent market crisis.

It quickly emerged that 3AC was dealing with a serious monetary crisis, leaving the fund with couple of alternatives besides extreme restructuring. On Jun. 27, Voyager Digital provided the company with a $665 million notification of default. A British Virgin Islands court then purchased the company to liquidate its possessions. 3AC declared Chapter insolvency in New York last Friday.

Teneo Restructuring, the company charged with liquidating 3AC, is leaving no stone unturned in its examination of the fund's illiquid wealth. Recently, it was commonly reported that Zhu had actually independently noted a Singapore residential or commercial property he and his spouse had actually bought for $35 million and designated to their three-year-old child in December2021 As liquidators turn their attention to 3AC's possessions, Starry Night Capital, the NFT fund established by the company's creators in 2015, might become their next target.

Starry Night Capital

Starry Night Capital was introduced by Zhu and Davies in collaboration with the pseudonymous NFT collector VincentVanDough Making its public launching at the height of a duration of speculative NFT mania on Aug. 30, 2021, the fund intended to raise $100 million to purchase unusual pieces from popular, desired collections, together with special, culturally substantial, unique works from popular NFT artists.

Before Starry Night formally released, 3AC had actually been utilizing its own funds to gather Art Blocks NFTs from well-known generative artists such as Tyler Hobbs and Dmitri Cherniak, in addition to works from other sought-after collections like CryptoPunks. 3AC's purchases pressed the flooring rates of much of these collections to brand-new highs; as on-chain information exposed that the company had actually purchased into top-tier collections like Ringers and Fidenza, other collectors hurried to copy trade them, assisting their costs skyrocket.

However, the company's most significant purchase was yet to come. On Aug. 27, the fund stunned NFT lovers worldwide when it bought Ringers #879 for 1,800 ETH (worth approximately $5.9 million at the time) from fellow collector Peter Molick, understood in the NFT area as pixelpete Bending the purchase to his Twitter fans, Zhu tweeted an image of the striking NFT with the caption "Thesis: we like the Goose."

" Ringers #879" by Dmitri Cherniak (Source: Dmitri Cherniak/OpenSea)

The Ringers #879 sale was a record-breaker for OpenSea NFT sales at the time. 3AC didn't stop there. Under the Starry Night Capital banner, Zhu, Davies, and VincentVanDough continued to invest huge on NFT art. The fund's noteworthy purchases consisted of " Pepe the Frog NFT Genesis" purchased for 1,00 0 ETH, XCOPY's " DANKRUPT" purchased for 469 ETH, and Robbie Barrat's " AI-Generated Nude Portrait # 7 Frame #184" purchased for 300 ETH.

With many distinct, distinctive pieces, it's challenging to put a worth on Starry Night's collection at its peak. CoinMetrics scientist Kyle Waters quotes the fund invested over $21 million on the NFT platform SuperRare alone. Including the countless ETH Starry Night dropped on other markets like OpenSea, the overall invest comes closer to the $100 million the fund apparently began with.

Despite on-chain proof revealing Starry Night making countless dollars worth of NFT purchases, just one company has actually openly revealed investing in the fund as part of its $100 million raise. KR1 PLC, a European digital property investment firm, apparently staked $5 million in Starry Night Capital to acquire direct exposure to the fund's portfolio of high-value NFTs. With this in mind, it's unidentified just how much of Starry Night's liquidity originated from 3AC and its creators, and just how much was offered by external financiers.

Starry Night Goes Dark

As news of Three Arrows Capital's liquidity problems made the rounds on social networks in June, observers kept a close watch on the company's associated jobs to try to find indications of contagion.

The very first tip that Starry Night might be dealing with concerns began Jun. 15, when Waters explained on Twitter that the fund had actually moved its whole collection of NFTs gotten through SuperRare to a brand-new address. "The brand-new wallet appears to have some linkage to other 3AC wallets however it's uncertain up until now what's going on," Waters stated, hypothesizing that the transfers might have been carried out in preparation for liquidation or over the counter sales to another celebration.

As the information of the relationship in between Starry Night and 3AC stay uncertain, observers have actually been delegated hypothesize over the fate of the fund's NFT. Some, such as amatus' Head of Trading Strategies John Hartery, assert that Starry Night's possessions are siloed, implying it would be not likely that they might be utilized to service 3AC's financial obligations. While 3AC introduced Starry Night, it's most likely that the earnings from any NFT sales would be dispersed to the fund's liquidity companies instead of 3AC's financial institutions.

However, if 3AC contributed a considerable quantity of liquidity to Starry Night, liquidators might require the sale of a few of the fund's NFTs to make its stake liquid. To prevent such a scenario, another celebration would likely require to reach an arrangement to purchase 3AC's stake from them straight. Under the existing scenarios, it appears not likely that Starry Night's NFTs will be liquidated in the instant future. The nontransparent nature of the fund's agreements and support, combined with the current wallet motions, implies a sell-off can not be ruled out.

If Starry Night does ever offer any of its NFTs, the collection has some method to go to reach its previous purchase worth, especially provided current market conditions. Many of the fund's NFTs have some historic significance or obtain their worth as special examples from popular collections. When Starry Night purchased pieces such as " Pepe the Frog NFT Genesis" and AlphaCentauriKid's " til death do us part," it likely did so with the thesis that the crypto area would grow significantly over the next couple of years, suggesting early examples of special NFT art might end up being extremely demanded. In the past, 3AC has actually talked about how it generally embraced a long-lasting outlook for its financial investments. It's not likely Starry Night had any objective of offering pieces from its collection for lots of years-- if ever.

Starry Night introduced throughout crypto's so-called "NFT summer season," and the flooring rates of the majority of the NFT collections it purchased have actually given that dropped in ETH terms. ETH has actually likewise dropped in dollar terms, implying NFTs that formerly struck excessive evaluations are now trading for portions of their all-time highs. In the present market decline, a forced liquidation would likely lead to a considerable recognized loss for Starry Night and bring an unfortunate end to the fund's pioneering financial investment method.

In the occasion that Starry Night is purchased to liquidate, it might possibly offer other collectors a once-in-a-generation chance to purchase a few of the most desired NFTs on the marketplace at greatly affordable costs. Such an occasion would likewise send out shockwaves through the NFT area, most likely pressing down the flooring costs for collections that Starry Night is greatly exposed to. While 3AC overcomes its liquidation, the NFT neighborhood will need to wait to see if among the world's most distinguished NFT collections will succumb to what is probably the harshest crypto bearishness to date.

Neither Three Arrows Capital, Starry Night Capital, nor VincentVanDough had actually reacted to Crypto Briefing's ask for remark at press time.

Disclosure: At the time of composing this function, the author owned BTC, ETH, and a number of other cryptocurrencies.

The details on or accessed through this site is acquired from independent sources our company believe to be precise and trustworthy, however Decentral Media, Inc. makes no representation or service warranty regarding the timeliness, efficiency, or precision of any info on or accessed through this site. Decentral Media, Inc. is not a financial investment consultant. We do not offer customized financial investment suggestions or other monetary recommendations. The info on this site goes through alter without notification. Some or all of the info on this site might end up being out-of-date, or it might be or end up being insufficient or unreliable. We may, however are not obliged to, upgrade any out-of-date, insufficient, or incorrect details.

You need to never ever make a financial investment choice on an ICO, IEO, or other financial investment based upon the details on this site, and you ought to never ever analyze or otherwise depend on any of the details on this site as financial investment recommendations. We highly advise that you speak with a certified financial investment consultant or other competent monetary expert if you are looking for financial investment guidance on an ICO, IEO, or other financial investment. We do decline payment in any kind for evaluating or reporting on any ICO, IEO, cryptocurrency, currency, tokenized sales, securities, or products.

See complete terms

Three Arrows Capital Caught Lying to Singapore Authorities

News

The Monetary Authority of Singapore has actually reprimanded Three Arrows Capital for supplying incorrect ownership info and surpassing the nation's allowed properties under management limit. MAS Reprimands Three Arrows Capital Three ...

Three Arrows Capital Caught Lying to Singapore Authorities

Court Orders Three Arrows Capital to Liquidate Assets: Sky News

News

A court in the British Virgin Islands has actually purchased the liquidation of crypto hedge fund Three Arrows Capital, Sky News has actually reported. 3 Arrows Capital Reportedly Facing Liquidation Three Arrows Capital ...

Court Orders Three Arrows Capital to Liquidate Assets: Sky News

Which Projects Could Be Affected by 3AC's Liquidity Crisis?

As reports of insolvency are plentiful, Crypto Briefing takes a look at which companies might be impacted by Three Arrows Capital's current liquidation occasions and prospective insolvency. The Three Arrows Crisis So Far "It's ...

Which Projects Could Be Affected by 3AC’s Liquidity Crisis?


Read More https://bitcofun.com/3ac-is-broke-whats-next-for-its-multi-million-dollar-nft-collection/?feed_id=28211&_unique_id=62cf0be054cad

Wednesday, July 6, 2022

What's happening with Bancor?

Cryptocurrencies

One of the greatest DeFi procedures on the marketplace has actually paused its impermanent loss security, stimulating reports of a liquidity crisis. The Bancor group spoke to CryptoSlate about what triggered the choice to stop ILP and the actions the procedure is requiring to avoid these issues in the future.

4 minutes read

Updated: June 22, 2022 at 12: 45 am

cryptocurrencies What’s going on with Bancor?

Cover art/illustration by means of CryptoSlate

Want to deal with us? CryptoSlate is working with for a handful of positions!

Bancor, a decentralized AMM and exchange, has momentarily paused its impermanent loss security function to secure the procedure and its users from "manipulative habits." In an statement released on June 19 th, Bancor stated that it was positive the procedures will protect the procedure while it deals with presenting much better securities.

However, the statement was rapidly followed by reports about a possible solvency crisis at Bancor that was framed as a "user security preventative measure." Still injuring from the Terra/LUNA fallout and the continuous crisis with Celsius, the crypto market is swarming with speculation about how Bancor will fix its liquidity problems.

CryptoSlate talked with the Bancor group about the truthfulness of these claims, the occasions that resulted in their choice to stop briefly impermanent loss defense, and the actions they were requiring to avoid comparable problems in the future.

Cryptocurrencies Bancor is attempting to avoid blowback from the Celsius crisis

On June 19 th, Bancor revealed that it will briefly pause its impermanent loss security (ILP) function. Trading will stay active on all liquidity swimming pools on the network and users who stay in the procedure will continue making yields. When ILP is reactivated, they will have the ability to withdraw their fully-protected worth. While withdrawals from the procedure have not been impacted, Bancor stated that it stopped briefly brand-new deposits into its liquidity swimming pools to "avoid confusion."

According to the business's post, Bancor has actually signed up abnormalities in its information and has factors to think that they're an outcome of manipulative habits.

" Therefore, we are taking vibrant steps to safeguard the procedure by briefly suspending IL defense and other actions to restrict more direct exposure," it stated in the statement.

However, reports about a possible liquidity crisis at Bancor spread out like wildfire right after the statement. The platform was implicated of purchasing time to determine how to stay solvent after sustaining losses on its native BNT token and minimizing the intensity of the problem.

what is the point of impermanent loss defense if it simply vanishes when u most require it LOL pic.twitter.com/GAJyhr6Tib

-- Cobie (@cobie) June 19, 2022

Some even think that Bancor is bound to wind up in a death spiral, as its ILP system compensates liquidity suppliers by minting brand-new BNT, moving the expense to BNT holders through inflation.

Bancor's shell video game of IL hiding is collapsing. They print brand-new BNT to compensate undersea LPs and call it "IL security". The expense is moved to BNT holders through inflation, which triggers more IL to all other BNT sets, and causes additional inflation. A death spiral. https://t.co/MbqPiL3sKB

-- Hasu ⚡ (@hasufl) June 20, 2022

Bancor validated reports that the current Celsius crisis was at least partly accountable for the concerns with IL on the platform. The business stated that the expense of supplying BNT benefits to liquidity service providers has actually been enhanced by the current insolvency of "2 big central entities," which lots of think describes Celsius and Three Arrows Capital.

These 2 entities were "essential recipients" of BNT liquidity mining benefits, having actually been veteran liquidity companies in Bancor v2.1. To cover their liabilities, these entities have actually suddenly liquidated their BNT positions and withdrawn large amounts of liquidity from the system. At the exact same time, an "unidentified entity" has actually opened a big brief position on BNT, Bancor discussed in the post.

While this would be a workable concern for a procedure with varied liquidity swimming pools, this is a severe threat for Bancor as all of the liquidity sets on the procedure protest its native BNT.

The choice to keep trading open while disliking deposits was likewise greatly inspected. Some critics stated that this allows BNT holders to dispose the tokens, triggering an even larger disparity in the liquidity swimming pools that now have no IL security.

Cryptocurrencies Bancor reacts to debate

The Bancor group fasted to react to the debate surrounding its choice to stop briefly IL defense. Nate Hindman, the procedure's head of development, stated that the statement had no intent of minimizing the seriousness of the scenario Bancor dealt with. On June 20 th, Bancor's item designer and head of research study Mark Richardson talked about the ramifications of the time out at length in a Twitter AMA.

Richardson discussed that the choice to keep trading open was an useful one, as reactivating IL security would need rebalancing over 150 liquidity swimming pools. Stopping brand-new deposits, nevertheless, was an ethical choice-- Richardson stated that it would not be reasonable to accept brand-new liquidity from users while the circumstance stays unsolved.

Nate Hindman, the chief of development at Bancor, informed CryptoSlate that there's no space for speculation about Bancor's solvency.

" Everything is on-chain. You can see just how much the procedure requires to pay in IL insurance coverage. We are not a central procedure where it is a black box and a person can take dangers with user funds. This openness into precisely just how much IL insurance coverage is owed is what assisted us rapidly recognize the circumstance and take emergency situation action paid for by the DAO to stop briefly the insurance coverage function on withdrawals."

When it pertains to allegations about the sustainability of Bancor's IL defense system, Hindman stated that there was a great deal of confusion surrounding its insurance coverage design.

" Some individuals believe we make up for impermanent loss simply by printing more BNT. That's not rather real. In truth, Bancor uses its liquidity service providers impermanent loss insurance coverage in return for a percentage of the trading costs made on the platform."

The procedure has 2 methods of producing these costs, with the very first being Bancor's protocol-owned liquidity. Bancor stakes BNT in its swimming pools and utilizes the charges made from staking to compensate users for any IL they sustain. The 2nd method of creating charges is through a protocol-wide cost that takes 15% of all trade income on the network and utilizes the costs to purchase and burn vBNT.

The choice to stop briefly withdrawals was an outcome of a "ideal storm of macro occasions" that culminated with the fast discarding of BNT liquidity mining benefits that were "exceedingly provided" over a duration of 18 months. Hindman stated that Bancor chose to avoid a handful of big gamers from disposing their stockpiles of BNT benefits and withdrawing their big liquidity stakes to safeguard specific users of the procedure.

" Excessive costs on BNT liquidity mining benefits throughout the life time of Bancor v2.1 put enormous tension on IL security in the middle of an ideal storm of macro occasions. That was the initial sin-- spending beyond your means on liquidity mining benefits," Hindman informed CryptoSlate.

He kept in mind that while Bancor is still positive in the toughness of its IL security design even in these severe conditions, the procedure required to safeguard itself from the extreme disposing of BNT and the huge brief gotten on its native token.

The Bancor group is working all the time on getting the IL security system completely back online with much better securities, Hindman stated, however could not supply any more information regarding when that will take place. Bancor likewise acknowledged the requirement for much better open-source analytics that would make it possible for the neighborhood to examine emerging threats and respond in time to prevent function shutdowns.

Posted In: Analysis, DeFi


Read More https://bitcofun.com/whats-happening-with-bancor/?feed_id=27275&_unique_id=62c668e513910

Monday, April 4, 2022

What’s behind the increase in companies offering crypto wages?

Adoption

Even cost volatility isn't moistening the interest to get paid in crypto.

Samuel Wan • Jan. 6, 2022 at 8: 30 am UTC • 2 minutes checkout

 What’s behind the rise in employers offering crypto salaries?

Cover art/illustration through CryptoSlate

 Symbiosis

As reported by NBC New York, more and more young experts desire to get paid in crypto. And, in a quote to lure and keep skill, forward-thinking companies are conference this need.

Even rate volatility isn’t moistening the interest to get paid in crypto, leading lotsof to marvel what’s driving this pattern.

Employers reacting to needs of young experts

A flurry of sports stars, and even politicians, have revealed getting paid in crypto in current times.

The NBC New York sector started with a promotion from LA Rams broad receiver Odell Beckham Jr., in which he revealed accepting his income in Bitcoin.

This is part of a offer with Cash App, in which Beckham Jr. endorses the payment company. He isn’t the just NFL professionalathlete to go this path. There’s likewise Green Bay Packers quarterback Aaron Rogers, New York Giants running back Saquon Barkley, and representing the NBA, Detriot Pistons point guard Cade Cunningham, to name a coupleof.

NBC New York selected up on the growing association inbetween sports and crypto. And inspiteof the volatility danger, they conclude that individuals are prepared to make the compromise for up side capacity. What’s more, they state these individuals “just desire to be like the professionalathletes.”

“It’s extremely unpredictable. But there’s a lot of up side to crypto and they desire to take benefit of those gains and the concept of getting paid in crypto, hello some individuals simply desire to be like the professionalathletes and performers we’ve simply been talking about.”

Similarly, young specialists with this frameofmind are bringup the possibility of getting paid in crypto. Employers at start-ups appear especially responsive to this concept.

“A lot of independent specialists, artists, individuals who working part-time and numerous tasks, they are looking into whether or not they can get paid in crypto, and they are taking benefit of it if it’s used.”

Betting the home on crypto

Former Carolina Panthers offensive takeon Russell Okung was the first NFL gamer to get his wage paid in Bitcoin in December 2020.

At that time, Okung started tweeting messages with a libertarian essence. He likewise went heavy on the point that crypto provides hope in a rigged system.

You can make “x” a year and watch it gradually deteriorate with inflation or you can secure your tough made cash with #bitcoin

— Okung 💯 (@RussellOkung) December 30, 2020

Fast forward to now, the Guardian justrecently released a piece entitled, “No pension. No costsavings. No future. No marvel we’re wagering the home on crypto,” in which author Rohit Thawani comprehensive his hasahardtime as a young expert attempting to get ahead.

Due to medical expenses, high lease, inflation, and so on, Thawani understood he was in a evenworse position than his momsanddads ever were. He postulates that crypto’s increasing appeal, is in part, the outcome of young individuals looking for a service in the mayhem that is modern-day life.

“Cryptocurrency is our opportunity to rage versus that maker.”

That being so, as the monster system grows larger, which it will with more cash printing, low-cost financialobligation, fractional reserve banking, rehypothecation, andsoon, it’s a certainty that more individuals will come to crypto looking for a service.

Get your everyday wrap-up of Bitcoin, DeFi, NFT and Web3 news from CryptoSlate

It's complimentary and you can unsubscribe anytime.

Get an Edge on the Crypto Market 👇

Become a member of CryptoSlate Edge and gainaccessto our unique Discord neighborhood, more special material and analysis.

On-chain analysis

Price pictures

More context

Join now for $19/month Explore all advantages


Read More. https://bitcofun.com/whats-behind-the-increase-in-companies-offering-crypto-wages/?feed_id=13931&_unique_id=624b0dd0092d4

Wednesday, March 30, 2022

What’s Up With S2F? — A Look At The Popular Bitcoin Model

One of the most fascinating aspects of bitcoin is its historical meteoric price rise. Is bitcoin going to continue on this historical path or is growth going to slow, or even halt?

The stock-to-flow (S2F) model, put forward by PlanB, suggests that bitcoin’s future price can be forecast quite precisely and that the price will continue a steady and impressive path upwards, with approximately tenfold returns every four years. The S2F model has attracted a lot of attention, and PlanB has amassed an impressive number of followers (1.7 million at the time of writing).

Perhaps in part due to its popularity, the model has more recently been met with a lot of criticism. An example of such criticism is a harshly-worded recent article published in Bitcoin Magazine. Also, in July 2020, Eric Wall put together a collection of criticisms.

It appears that most people find themselves in either of two camps: the “pro” S2F and the “con” S2F camps. How should we position ourselves?

Before I go on: I have written negatively about the S2F model since 2019, when I predicted that the S2F model’s predictions would prove too bullish. I have also exchanged with PlanB both publicly on Twitter (e.g. here), and privately. I have coauthored a more mathematical article together with InTheLoop, clarifying why we both think the S2F model is too bullish. It might therefore come as no surprise that I am not exactly in the S2F camp. However, I have also noticed that some of the criticisms towards the S2F are invalid. Other criticisms purport to deal a death blow to the S2F model, whereas in fact, they do not. I therefore hope to add some clarity. It is important to be right for the right reasons, because correct principles are our only chance of being right in the future.

The S2F Model

The S2F model states that the price of bitcoin is driven by its scarcity. As the halvings ensure that bitcoin becomes ever more scarce, its price should continuously increase. The relation between scarcity and price is mathematically defined (using two empirically estimated parameters) and roughly forecasts a tenfold increase in price every four years. This gives us a price of $100,000 per bitcoin for this halving epoch, $1,000,000 for the next, and so on.

What’s wrong with this model? Let’s look at some arguments that are put forward to discredit the model:

Tautological Specification

In their recent Bitcoin Magazine article, Level39 had this to say regarding the S2F model:

“Notice how the function says ‘market value’ equals a function of Stock-to-flow? This is a model misspecification with tautological logic and therefore statistically invalid, for the simple reason that ‘market value’ decomposes to ‘stock / price’ while ‘stock / flow’ is on the other side of the equation. In layman’s terms PlanB is essentially asserting that ‘stock is a function of stock.’ A tautology is a trivial statement that is true under any circumstances. It’s like saying a banana is a kind of banana. Of course stock is a function of stock. This is why the data fits, but is scientifically worthless. Tautologies are true but do not tell us anything useful. Rather, they are true because of the meanings of the terms.”

But is this really so? Has PlanB really given us a tautological formulation that doesn’t tell us anything useful, a bit as if Isaac Newton had told us that F = F? Is stock really on both sides of the equation?

The S2F model as formulated by PlanB attempts to approximate the market cap of bitcoin using stock-to-flow as an input variable (where a higher stock-to-flow indicates higher scarcity). Two parameters (a and b) must be empirically estimated so as to get the best fit. Writing this down, it at first might appear that indeed stock appears on both sides of the equation (see the second and third lines, below). However, by simply rearranging terms, we see that this is fine: the price of bitcoin is on the left-hand side of the question, stock and flow on the right side.

log market complicated math ting

We have clearly demonstrated that the S2F model is not afflicted by a tautology that renders it mathematically invalid. Still, there is one more point to make. Level39 goes on to explain:

“PlanB could avoid the tautology by having price alone on one side of the equation and perhaps build a regression of price on flow or stock to flow, but the fit would be different without changing the parameters.”

In other words, if PlanB had attempted to model (the log of) the price using a linear function of stock-to-flow instead of the market cap, the stock would not appear on both sides of the equation, and hence the supposed tautology would disappear. In other words, in order to get a price forecast based on stock-to-flow, we could either:

  1. Model the market cap, and translate the market cap back to prices. This is what PlanB did, and Level39 sees a tautology here, or:
  2. Model the price directly. Level39 sees no tautology here.

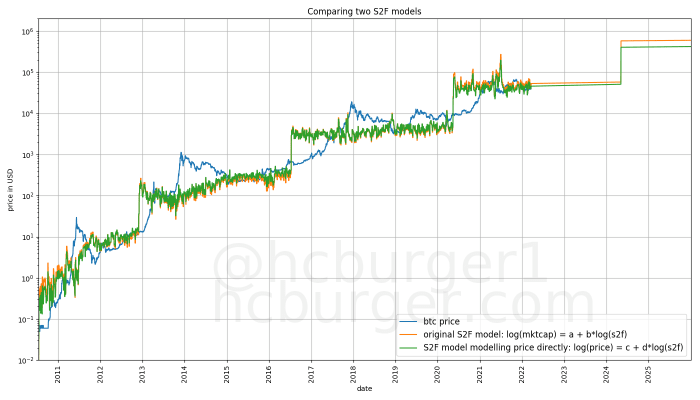
Level39 insinuates that A would produce a much better fit than B because of the supposed tautology. But is this really the case? In the below plot I have compared both models:

comparing two s2f models

We see the two models are extremely similar to each other. There is no enormous difference in the quality of fit between the two models. Hence, even if there were a tautology in the original S2F formulation (there isn’t), the point would be quite trivial, since it would not materially matter. The model could be rewritten to approximate price instead of market cap and the result would be almost identical.

Hence, the whole argument regarding a tautology is clearly moot. No death blow to the S2F model here.

Autocorrelations

Another argument against the S2F model I have frequently heard is also mentioned by Level39:

“The other problem is that the model is autocorrelated, where the results of today’s value is a function of yesterday’s value. When you adjust for that, the R-squared (R2) value is zero. Thus, scientifically speaking, stock-to-flow is nonsensical and cannot be used to model price.”

Another way of stating this is to say that instead of trying to find a relation between stock-to-flow and price (or market cap) one should instead try to find a relation between changes in stock-to-flow and changes in price (or market cap). The claim is that changes in stock-to-flow on a day-to-day basis do not appear to cause a change in price on the same time scale, and hence there supposedly can’t be a causal relationship between stock-to-flow and price, meaning that the S2F model must be incorrect.

But is this really the case? Large changes in stock-to-flow happen only once every four years. The variations in stock-to-flow between the halvings are mostly small and have a strong element of randomness. Must we really expect that both small and large changes in stock-to-flow cause a change in price? This would mean that we are assuming that there is a linear response, which need not necessarily be the case: It could be argued that only large changes in stock-to-flow are meaningful.

Hence, the argument of auto-correlations also does not yield a death blow to the S2F model.

Ad Hominems

Another argument against the S2F model I frequently encounter is PlanB’s behavior on Twitter. Level39 has this to say about it:

“[… ] anyone who points out a flaw, potential problem, has a valid question or even “likes” a valid inquiry into the validity of his assertions is blocked [by PlanB] […] If PlanB wants to honestly claim that his models have a scientific R2 value in the high 90s, then he cannot be blocking and censoring valid criticism that shows otherwise.”

The answer I have to this is that PlanB can do whatever he feels like on Twitter. He is not obliged to behave in a specific way or to answer any particular questions. His behavior has no impact on whether the S2F model is valid or not.

In addition to this, my own experience with PlanB has been very different than the one described by Level39. I have openly criticized his model on Twitter in 2019 (you can witness such a discussion here), and have not been blocked. We have exchanged privately and I cannot characterize PlanB’s behavior as anything other than very friendly.

I have heard of events when people were blocked by PlanB, but I am not surprised by this: He has to manage an audience of 1.7 million people, which cannot be easy. In any event the ad hominem argument says nothing about the validity of the S2F model and should be disregarded.

Lack Of Cointegration

There has been a long debate regarding whether a certain property known as cointegration (pronounced co-integration, not coin-tegration) exists between stock-to-flow and the price of bitcoin. Cointegration is supposed to hint at a causal relation between the two variables. When it ultimately came out that the cointegration property does not exist between stock-to-flow and price, this was interpreted as meaning that a change in stock-to-flow cannot possibly cause a change in price. A death blow to the S2F model! But is that really the case?

I had never heard of cointegration prior to 2019, when studying the stock-to-flow model. It is a concept that is widely used in econometrics, but not in any other fields (as far as I am aware). For example, in March 2020 Judea Pearl, the de facto inventor of causal statistics and author of “The Book of Why” had not heard of cointegration either! He gave two clarifying statements that cointegration might give an indication that there is causal relation, but that it by no means implies a causal relation. In 2022, Pearl again lamented that no one was able to satisfactorily explain the concept of cointegration to him.

The fact that the inventor of causal statistics did not know about the concept of cointegration is telling: The importance of cointegration seems overblown. The lack of cointegration might perhaps hint at trouble for the S2F model, but it should not be considered a death blow.

Summary Of Anti-S2F Arguments

The arguments against the S2F model we have seen so far either have no merit (supposed tautology, ad hominem attacks), or perhaps weaken the credibility of the model but do not rule it out (lack of cointegration, autocorrelations).

What we should do is rely on empiricism: Is the S2F model able to predict future prices correctly? This is the litmus test for any price model.

An Empirical Look At S2F

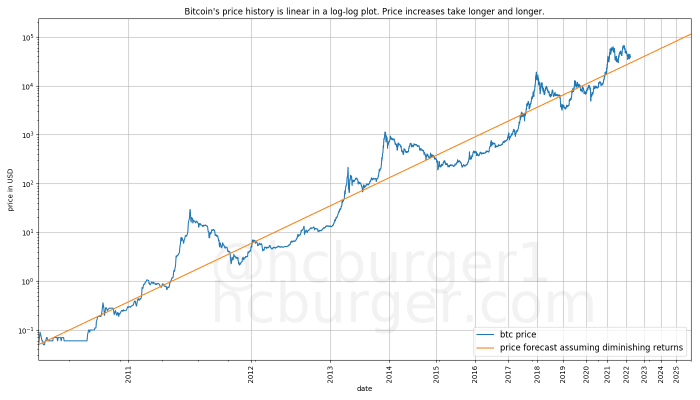
I have created a bitcoin price model called the power-law corridor of growth which relies on the observation (which I owe to Giovanni Santostasi’s reddit post) that bitcoin’s price follows a straight line when plotted using an x-axis that is scaled logarithmically.

bitcoin price history is linear

This simply means that bitcoin’s price growth is slowing down. Whereas it used to take only about a year for the price to appreciate ten-fold, it now takes several years. Returns are diminishing, and I expect this trend to continue into the future.

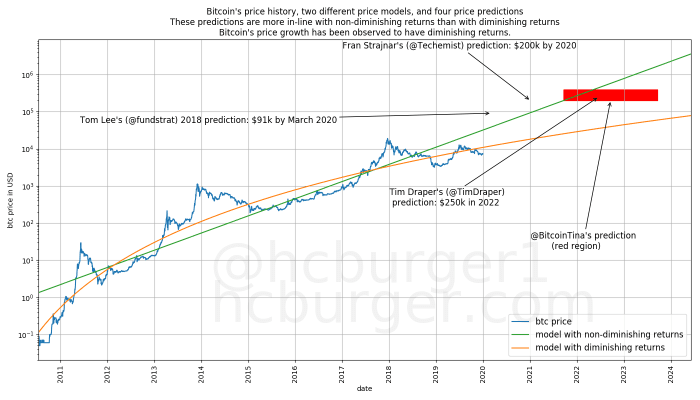
Yet, many people seem to assume that bitcoin’s price will behave similarly in the future as it did in the past. In other words, they expect price increases to happen at the same pace as in the past. I have published the below plot in an article at the end of 2019. Various people have made predictions apparently based on the assumption of nondiminishing growth (roughly represented by the green line). I predicted that these forecasts would prove to be too bullish, and that the price would more closely follow the orange line, which is governed by diminishing returns.

bitcoin price history two different models

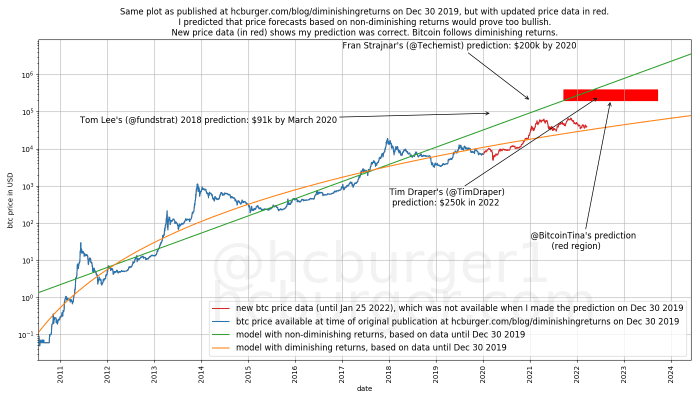
How has my prediction fared? The next plot is the exact same as the previous one, but with the addition of price data (in red) which is now available and that was not available at the time I made the prediction.

asme plot as published 2019

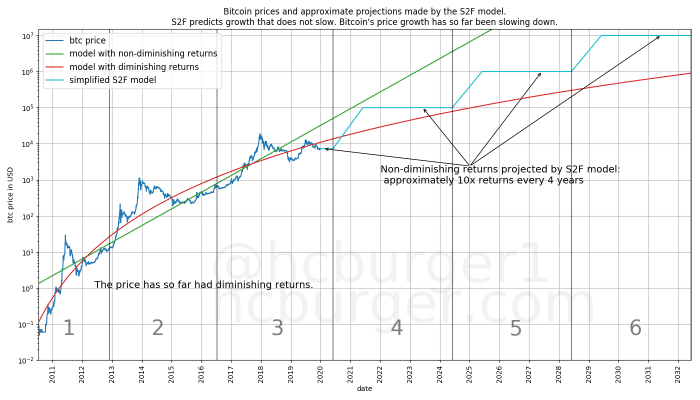
My 2019 prediction proves to have been prescient. What does this mean for the S2F model? In the same article I explained that S2F forecasts nondiminishing growth, and that I therefore also expect it to be too bullish, similarly to the forecasts made by the individuals above. Below is the plot that I published:

bitcoin prices and approximate projections

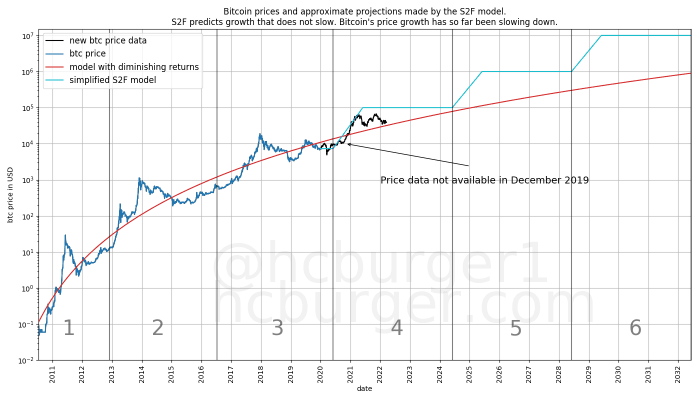
The same plot can now be filled in with more recent price data:

same plot filled with price data

Again, it would appear that bitcoin’s price more closely follows a trajectory with diminishing returns. I therefore expect the price to move further and further away from the S2F forecasts in the long term.

The more mathematically-inclined reader might be interested in an article I coauthored with InTheLoop which explains in more detail how the shape of the S2F price curve does not match the actual price data well.

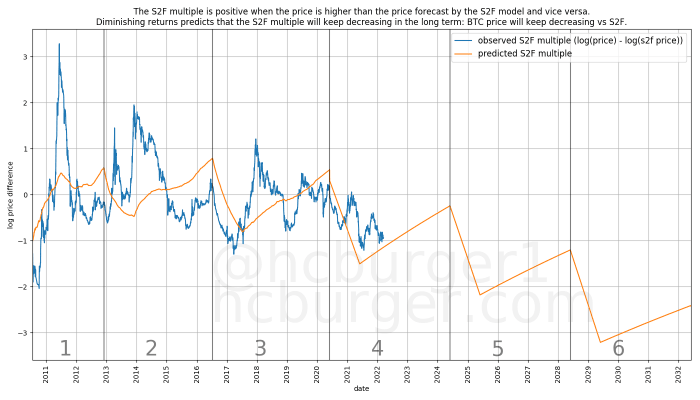
The popular Twitter handle s2fmultiple tracks how the price is performing compared to the S2F forecasts. The metric is referred to as the S2F multiple. A multiple greater than 0 means that the price is higher than the S2F multiple, and vice versa.

The history of the S2F multiple so far looks like the below plot. There have often been high values before 2015, but not so much after that. This is a hint that the price is not quite catching up to the S2F model forecasts (and also that the shape of the S2F price curve does not match actual price data well).

By comparing my own power-law corridor of growth forecasts to the S2F model, I am able to compute the trendline of how I expect the S2F multiple to evolve in the future:

bitcoin s2f multiple positive

Conclusion

The S2F model has been heavily criticized, often unfairly. I am highly confident that the S2F model will fail to predict bitcoin’s price adequately, but my main argument is simply that the shape of the S2F price forecasts is incorrect and too bullish. The S2F model forecasts nondiminishing growth, which is not justified by empirical observations, which instead strongly hint at diminishing growth.

This does not mean that we should feel disappointed. Bright days lie ahead for the price of bitcoin. In my original article I have forecast a price of $100,000 per bitcoin no earlier than 2021 and no later than 2028, and $1,000,000 per bitcoin no earlier than 2028 and no later than 2037. I still expect these forecasts to come true.

This is a guest post by Christopher Burger. Opinions expressed are entirely their own and do not necessarily reflect those of BTC Inc or Bitcoin Magazine.


Read More https://bitcofun.com/whats-up-with-s2f-a-look-at-the-popular-bitcoin-model/?feed_id=13187&_unique_id=62442934cdc9e

Leading 7 Decentralized Derivatives Trading Platforms

Decentralized derivatives are a brand-new method for traders to trade crypto possessions without straight holding them. Read on to disc...